
Your insurance company has a product for you. It protects you against a rate increase — from your own insurance company.
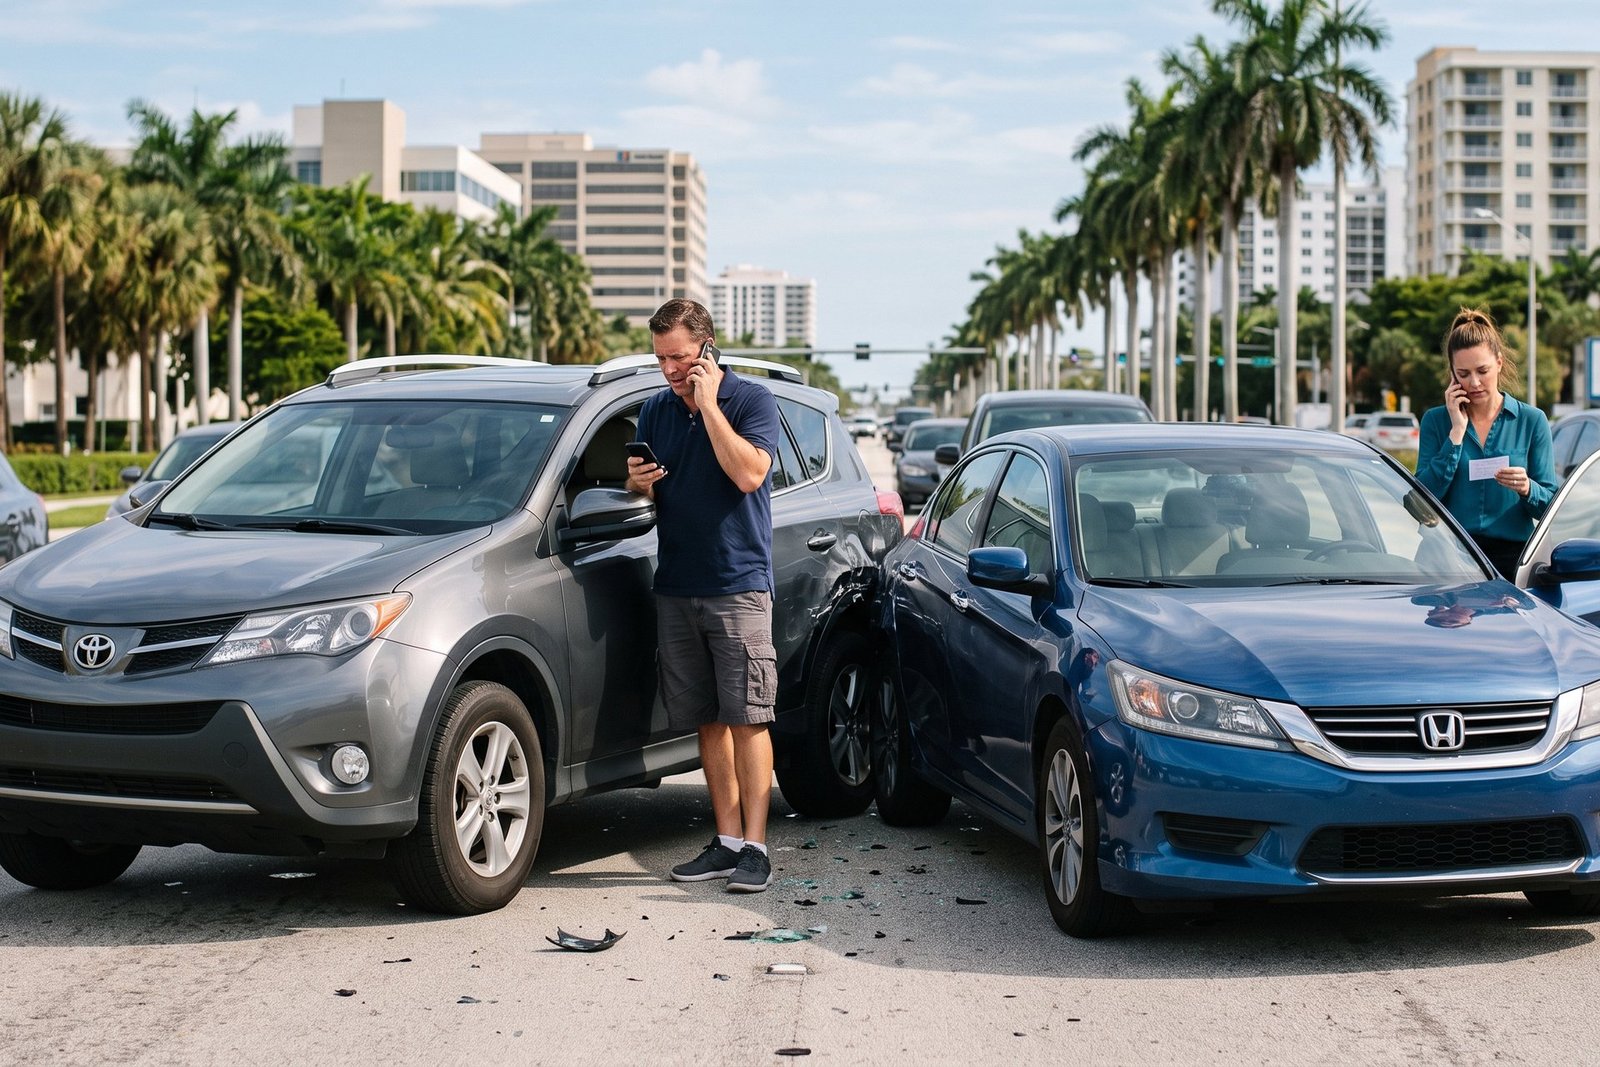
That’s accident forgiveness in a sentence. You pay your insurer extra money now so it promises not to punish you later. It’s insurance on your insurance, sold by the same outfit that decides when to raise your rates.
I’ve been writing about this stuff since 1991, and I became a CPA a decade before that. Whenever a company invents a product that protects you from itself, my antenna goes up. Yours should too.
Now, I’m not going to tell you accident forgiveness is worthless. For some drivers it pays off. But the marketing is a lot simpler than the contract, and almost nobody reads the contract.
Here’s what’s in there.
1. You’re buying insurance against a bill, not a catastrophe
The whole point of insurance is to protect you from a loss you can’t absorb. A house fire. A lawsuit. A totaled car you still owe money on.
A premium increase, while unpleasant, isn’t one of those things.
The National Association of Insurance Commissioners says carriers can bump your premium by as much as 40% after an at-fault crash. On a typical policy, that hurts. It doesn’t bankrupt you.
Buy insurance for the disaster. Handle the annoyance yourself.
2. The free version can take five years to earn
Every carrier loves to advertise that accident forgiveness might not cost you a dime. True — eventually.
GEICO, for example, hands it over free once you’ve gone five or more years without an accident. Progressive’s bigger version also wants five continuous years with the company, and a clean record on top of that.
So the reward for never crashing is a coupon you can use if you crash.
If you want it sooner, you buy it. Carriers don’t publish a standard price, which tells you something all by itself.
3. ‘Forgiveness’ sometimes means $500 and not a nickel more
This one floored me.
Progressive offers two flavors. The small version, which many new customers get automatically, applies only to a claim of $500 or less. The larger version — the one that covers a real wreck — is the five-year loyalty prize.
A $500 claim is a cracked bumper. Most people wouldn’t file it in the first place, because filing it is what triggers the surcharge.
You’re being sold a shield against a punch you should be ducking anyway.
One thing before we keep going — the financial world is louder and dumber than ever. Hot takes everywhere. Almost none of it is worth your time. I’ve spent 35+ years cutting through the noise so you don’t have to. Sign up for the free Money Talks Newsletter — 10 seconds, no spam, just the stuff that matters.
4. The accident doesn’t disappear; it just gets ignored
Here’s the part the ads skip.
Forgiveness doesn’t scrub the crash from your driving record or your claims history. Massachusetts regulators put it plainly on the state’s own consumer page: Your insurer simply agrees to leave that accident out of its premium math.
The accident is still there. Everyone can still see it. Your current carrier is just choosing to look away.
That distinction matters enormously the day you decide to shop.
5. Switch companies and your forgiveness dies
This is the trapdoor.
Massachusetts warns consumers directly that a forgiven accident can be counted by your next insurer. Forgiveness is a promise from one company about one policy. It doesn’t travel with you.
So think through what you’ve actually bought. You paid extra to stay unpunished — but only if you stay put.
And staying put is expensive. Comparison shopping is the single biggest lever most drivers have, which is exactly why loyalty is one of the common car insurance shopping mistakes that quietly drains people for years.
An add-on that penalizes you for shopping isn’t protection. It’s a leash.
6. It’s usually per policy, not per driver
Got a teenager on your policy?
GEICO’s version covers the policy, not each person on it. Any eligible driver can use the benefit — once. After that, it’s gone for everybody.
GEICO also notes it may not apply to drivers under 21, which is a problem, because the statistically likeliest person in your household to need forgiveness is the kid who just got a license.
If that’s your situation, your money is better spent on the smart ways to save on teen auto insurance — good-student discounts, driving-monitor apps, a sensible car — than on a benefit your teen may not even qualify to use.
7. In some states, you can’t buy it at all
Availability is a patchwork. GEICO says its accident forgiveness isn’t offered in California, Connecticut or Massachusetts, and that the purchasable version isn’t sold everywhere either.
The NAIC also cautions that terms swing wildly between carriers. Some forgive one accident. Some forgive more. Some make you go years clean before the coverage even switches on.
If you can’t summarize your own policy’s rules in one sentence, you don’t know what you bought.
What to do instead
None of this means you should never take accident forgiveness. If your carrier throws it in free after five loyal years, take it. Free is a fine price.
But if someone’s asking you to pay for it, do the arithmetic first.
Start with the real number. Bankrate’s reporting on how much car insurers raise rates after an accident found average full-coverage premiums jumping from $1,738 to $2,299 after a serious at-fault crash — about $561 a year.
Now weigh that against paying every single year for a benefit you’ll probably never use, on an accident you probably won’t have.
This is the same math trap as those vanishing-deductible programs. Disappearing deductible plans don’t always save you money, and the pattern is identical: Pay a little forever, collect a little maybe.
Three moves beat it almost every time.
1. Shop the whole market, every year
The Texas Department of Insurance tells drivers that companies charge different prices for identical coverage, and that new customers often get discounts. Loyalty is a fee, not a virtue.
And now it’s easier than ever to shop your policies. For example, Insurify lets you compare real-time quotes side by side without spam. It takes minutes to check, and it costs you nothing. If you’ve got a minute, see if you’re overpaying right now.
2. Raise your deductible
Going from $500 to $1,000 can cut premiums roughly 9% on average. Bank the difference and you’ve built your own forgiveness fund — one that pays you when you don’t crash.
3. Don’t file small claims
If the damage is close to your deductible, pay it yourself. No claim, no surcharge, nothing to forgive.
There’s one more reason to slow down before adding coverage right now.
Car insurance costs finally stopped sprinting. Bureau of Labor Statistics data show the motor vehicle insurance index slipped 0.3% in July after a 2% drop in June.
That follows years of brutal increases. The NAIC pegged the 2023 average annual expenditure at $1,281.60, up more than 19% since 2019. Now the pressure is easing.
That’s the worst possible moment to bolt on a new monthly charge.
Insurance salespeople make more money when you buy more insurance. That’s not a conspiracy. It’s a paycheck. Just remember whose it is when someone offers to forgive you for a fee.
Read the full article here